All Categories
Featured
Understanding How Indexed Universal Life Benefits Secure ...

Evaluating Indexed Universal Life Policies for Retirement
Evaluating PPO and HMO Health Plans
Employee repayments will be tax-free if their private health plan offers minimum necessary coverage (MEC). Companies can compensate workers for out-of-pocket expenses and health insurance premiums, consisting of those for an HMO or PPO plan. Individual protection HRA (ICHRA): An ICHRA is also a stand-alone HRA, but it's offered to employers of all sizes and has no contribution limits.
Insurance in Ventura CA
They must have a qualifying kind of private health coverage to get involved. Employers can set various allowances based on worker classes for added customization. Group coverage HRA (GCHRA): Also referred to as an incorporated HRA, a GCHRA is for companies of any size who offer a group health insurance. Just employees registered in their company's group plan can get involved.
Insurance in Ventura CAWhile they have no maximum contribution limitations, the IRS doesn't allow reimbursements for monthly premiums. No matter whether it's utilized in coordination with an HMO or PPO plan, there's an HRA that can help staff members pay for their out-of-pocket medical costs and, in some cases, their medical insurance premiums. An HRA is a popular alternative choice over standard health advantages due to the fact that they're budget-friendly for employers and versatile enough for every single worker.
Reviewing 2026 Medicare Advantage Options
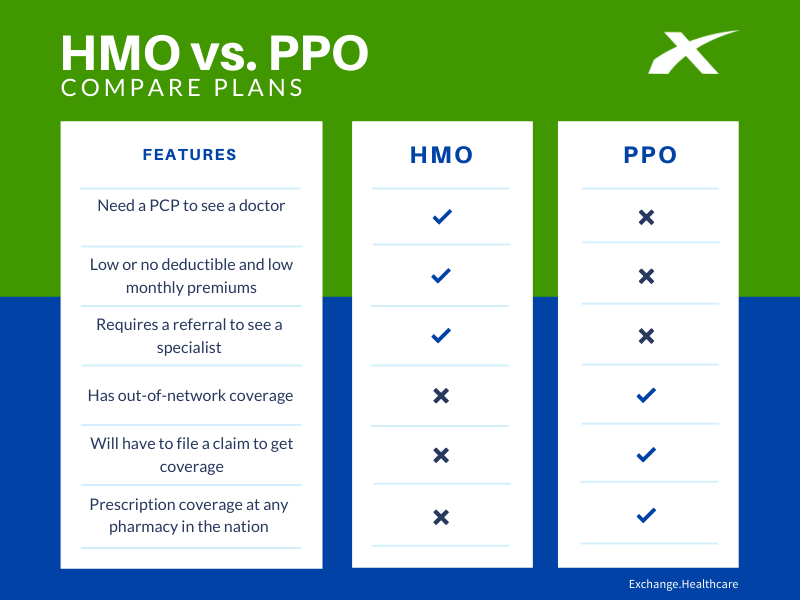
An HMO may be your finest bet if you're trying to find a plan with a low premium. A PPO strategy provides additional flexibility if you require more control over your healthcare. That's why investigating these plans carefully, including their pros, cons, and typical expenses, is the very best initial step you can take before deciding.

Latest Posts

Navigating Life Insurance Benefits for US Veterans
Understanding How Indexed Universal Life Benefits Secure Retirement

Direct Advice for Life Insurance Selection